Inside Quant Trading Labs

Everything you need to research markets systematically.

QTL brings together strategy research, historical evidence, AI workflows, Python, market data and portfolio research inside one connected environment — whether you are starting from zero or already building systematic strategies.

No programming or quantitative trading background is required to begin.
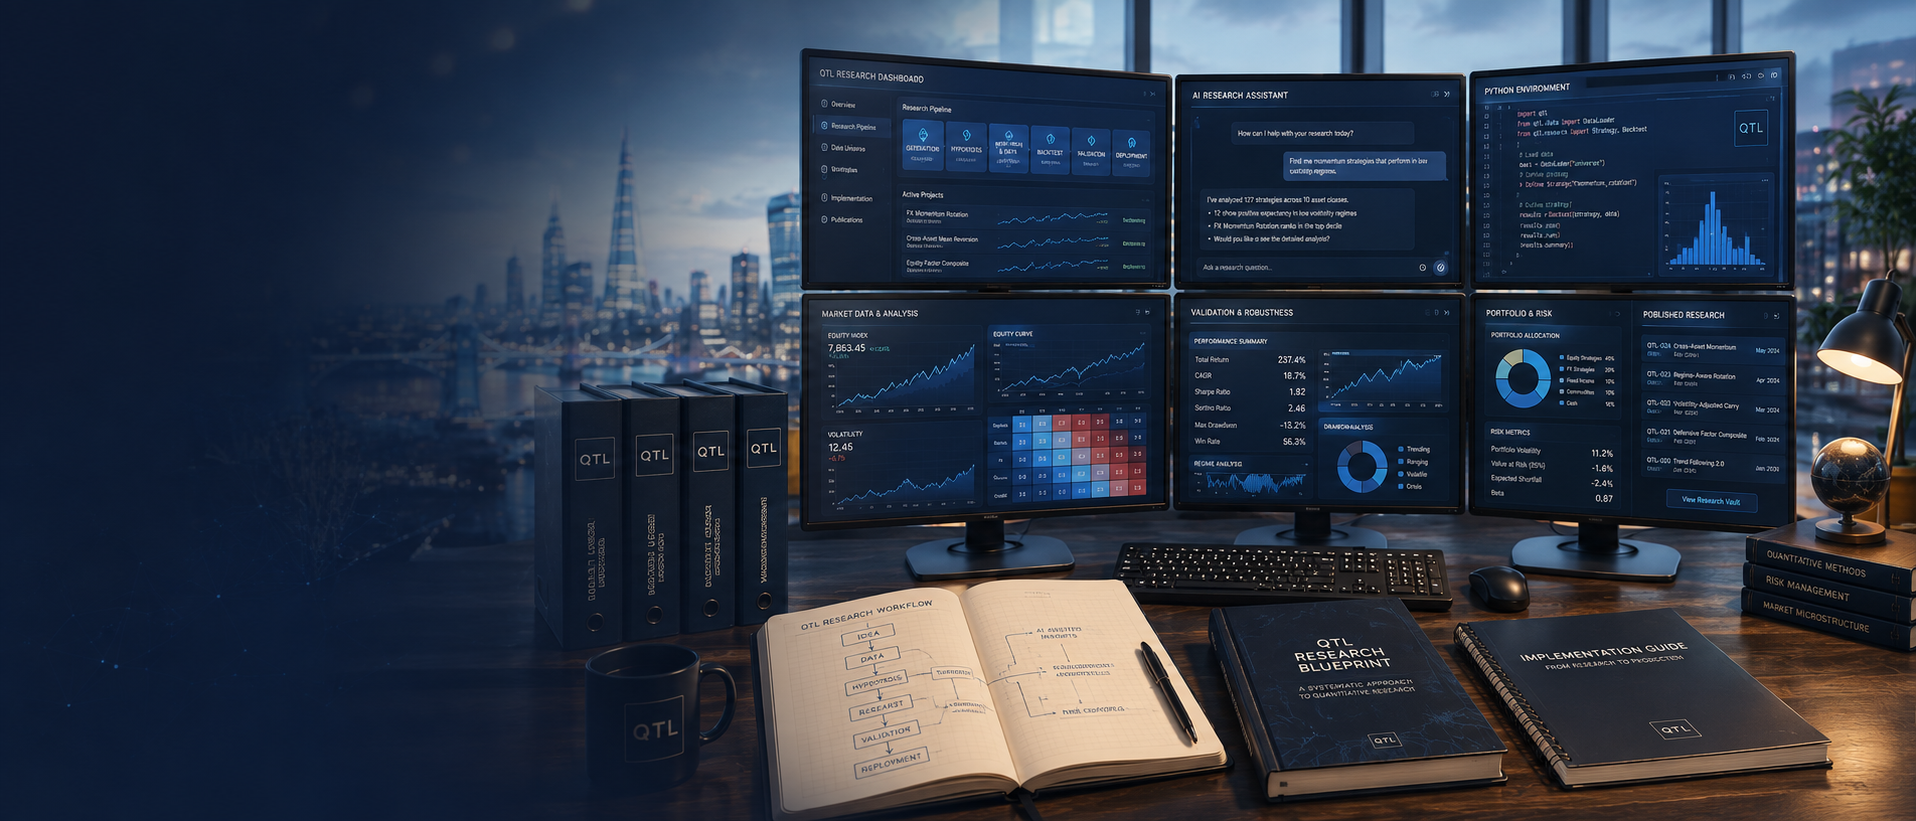
Quant Trading Labs quantitative research workspace showing AI research, Python, strategy validation, portfolio analysis and QTL research materials
One Connected Process

From raw market data to systematic execution.

QTL connects each stage rather than treating research, backtesting, coding and deployment as separate subjects.

Members can see how an observation becomes evidence, how evidence becomes a strategy and how validated research can eventually move toward portfolio construction and controlled implementation.

QTL Research Pipeline
From observation to implementation
Stage 01
Raw Market Data
Stage 02
Research
Stage 03
Evidence
Stage 04
Strategy
Stage 05
Portfolio
Stage 06
Production
Your Research Environment

The QTL Research Terminal

The Terminal is the central member workspace connecting QTL research, published strategies, market intelligence, publications, prompts and implementation resources.

Included With Membership

Your QTL command centre.

Move between research, evidence, strategy work, education and implementation without navigating disconnected products or downloads.

View membership
Research

Current investigations and published work

Strategies

Live Flip BB, OS1 and future research

Publications

Blueprints, manuals and notebooks

Prompts

Governed AI research workflows

Evidence

Backtests, validation and supporting analysis

Implementation

Code, deployment and live transition

Real Research Programmes

The QTL Strategy Labs

These are not simplified teaching examples. They are documented quantitative research programmes showing how market behaviour is investigated, challenged, validated and engineered.

QTL1 · Strategy Lab

Live Flip BB

From market-state research to a systematic strategy

Follow the research from raw M1 data through market-state modelling, release behaviour, event reconstruction, outcome analysis, exit research, portfolio construction and production engineering.

Raw M1 market data
Volatility and state research
BIND / release behaviour
Event reconstruction
Forward outcome analysis
Exit research
Portfolio construction
Risk allocation
Live-shadow architecture
Production engineering
Explore published research
QTL2 · Strategy Lab

OS1

Behavioural feature research from raw OHLC observations

Explore how OS1 developed from feature discovery into event families, directional testing, execution validation, robustness research, portfolio architecture and production handover.

Feature engineering
Structural relationships
Event families
Multi-horizon testing
MFE and MAE analysis
Instrument-specific behaviour
Execution validation
Robustness testing
Risk architecture
Production design
Explore published research
Learn the Method

The methodology behind the strategies.

Strategies are outputs. The transferable skill is learning how to conduct structured quantitative research repeatedly.

AI Quant Blueprint

Learn how QTL approaches markets before a strategy exists — from observation and hypothesis formation through falsification, experiment design, validation and implementation.

Observation
Hypothesis formation
Variable definition
Falsification
Experiment design
Statistical validation
Robustness
Overfitting control
Documentation
AI-assisted research
Explore the Blueprint

Research Operating System

Turn the QTL philosophy into a repeatable research workflow connecting research questions, evidence, validation, engineering and deployment.

Observe
Describe
Question
Measure
Challenge
Build
Validate
Engineer
Deploy
Explore the Methodology
Behind the Finished Strategy

The research that normally disappears.

QTL preserves the questions, failed experiments, prompts and decisions behind the finished systems so members can study how research actually evolves.

Research Notebooks

See the questions, experiments, mistakes and changes in direction that normally disappear when a completed strategy is published.

Original research questions
Failed hypotheses
Unexpected results
Alternative explanations
Validation decisions
Engineering problems
Portfolio discoveries
Changes in research direction

AI Prompt Library

Governed prompts developed to support actual quantitative research rather than generic strategy generation.

Dataset investigation
Market behaviour
Hypothesis design
Engineered features
Null hypotheses
Statistical tests
Robustness
Execution
Risk
Portfolio construction
Production architecture
Build and Reproduce

Research should be reproducible.

QTL connects the intellectual side of research with the technical tools needed to measure, test, simulate and implement it.

Python & Source Code

Research and implementation code supporting QTL investigations, backtests, validation and strategy development.

Dataset preparation
Feature construction
Event detection
Forward outcomes
MFE / MAE analysis
Backtesting
Portfolio simulation
Risk modelling
Reconciliation
Reporting

Historical Market Data

Work from structured historical market observations rather than starting with prebuilt indicators or unexplained signals.

Raw market observations
M1 research workflows
Structured historical datasets
Research-ready transformations
Reproducible analysis inputs

Portfolio & Risk Research

Understand what happens after an edge has been discovered — when strategies, instruments and capital interact.

Portfolio exposure
Pair selection
Concentration
Correlation
Position sizing
Risk caps
Drawdown control
Allocation
Strategy combinations
The QTL Research Journey

From question to production.

Every major QTL investigation follows the same broad research progression.

The process — rather than any individual strategy — is the foundation of Quant Trading Labs.

01

Observe

Identify recurring market behaviour without assuming the explanation.

02

Hypothesise

Turn an observation into a measurable proposition.

03

Measure

Define variables capable of testing the idea objectively.

04

Challenge

Search for alternative explanations and reasons the idea may be wrong.

05

Validate

Test across markets, periods, regimes and assumptions.

06

Engineer

Convert surviving research into deterministic rules and software.

07

Portfolio

Determine how the strategy interacts with capital and other opportunities.

08

Deploy

Move validated research toward controlled production architecture.

Built for Every Starting Point

You do not need to be a quant, programmer or successful trader to start.

QTL is designed for anyone who wants a more structured way to approach the markets. You can begin with no coding experience, no systematic trading background and no previous success building strategies.

The objective is to help you move away from long days watching charts and toward researching objective rules that can ultimately be tested, engineered and automated.

Starting From Zero

No quantitative experience? No problem. Learn the research process from the beginning, with AI helping explain concepts, structure investigations and support the technical work.

Tired of Discretionary Trading

Move away from feeling tied to the screen. Learn how observations can become objective rules that are researched and tested rather than relying on constant chart watching and manual decisions.

Never Written Code

You do not need to arrive as a programmer. Modern AI can help translate research ideas into Python, explain errors and support implementation while you focus on the quality of the research.

Already Trading

Bring your existing experience with you. Turn patterns, ideas and market observations you already recognise into hypotheses that can be measured and challenged objectively.

Already Systematic

Go deeper into validation, robustness, portfolio construction, AI research workflows and the engineering required to move from backtest to controlled implementation.

Want More Freedom

Build toward researched strategies capable of systematic execution. The objective is not to spend more time watching markets, but to develop rules that can be tested, engineered, automated and monitored with far less manual intervention.

You do not need to become a mathematician or software engineer. You need a structured research process, the right tools and a willingness to test what you believe.

What QTL Is
A quantitative research environment
A documented strategy-development laboratory
A structured research methodology
A collection of real research programmes
A growing toolkit for independent systematic research
What QTL Is Not
A signal service
A copy-trading platform
A black-box trading robot
A collection of secret indicators
A promise of effortless returns

Quantitative research contains uncertainty. QTL teaches you how to investigate it.

The Complete Environment

One membership. One research environment.

Strategy Research
Live Flip BB
OS1
Research Education
AI Quant Blueprint
Research methodology
Case studies
Research notebooks
Research Tools
AI Prompt Library
Python resources
Research frameworks
Portfolio and risk material
Research Infrastructure
Historical datasets
Research Terminal
Downloads
Implementation resources
Continuing Development

The environment continues to grow.

New research
New experiments
New tools
Strategy validation work
Terminal development
Publication updates
Quant Trading Labs

Research the market differently.

You do not need another trading strategy you cannot explain. Learn how systematic ideas are observed, tested, challenged, engineered and ultimately turned into reproducible quantitative research.

Research and educational content only. Historical or simulated results are not reliable indicators of future performance.